Health insurance guide: how it works and the rules on your side
One page that maps health insurance, from the basics to the rules that protect you
Health insurance pays your hospital bills, up to a limit, so one illness doesn’t wipe out years of savings. You pay a yearly premium. The insurer pays covered bills up to your sum insured. That’s the whole idea. Everything else is detail, and this page maps it.
Start with the basics. New to all this? Read the lesson on health insurance basics first. It covers the waiting period, the room rent limit, co-pay and the no claim bonus, in simple language.
How a claim reaches you. There are two routes. In a cashless claim, the insurer pays a network hospital directly. In a reimbursement claim, you pay first and claim it back. Our explainer on cashless vs reimbursement claims walks through both.
Five rules on your side. The Insurance Regulatory and Development Authority of India (IRDAI) sets rules every health insurer must follow. These five, from its May 2024 master circular, matter most when you buy.
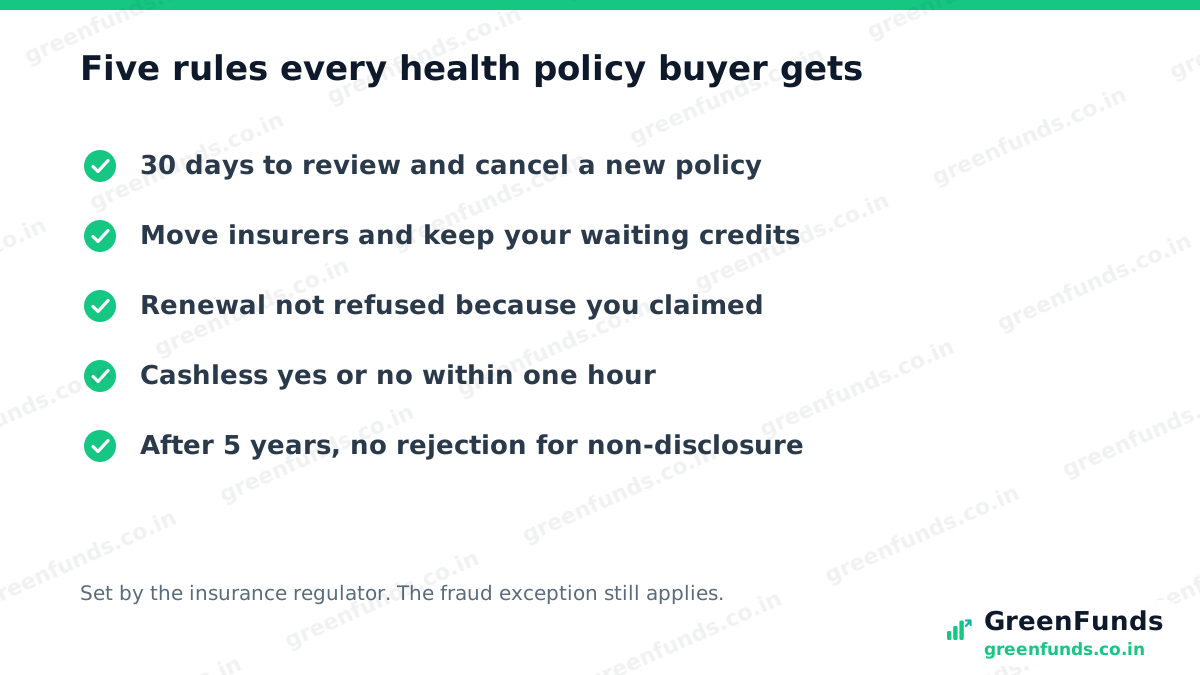
- A 30-day free-look period. You get 30 days from receiving the policy document to read it and cancel, for policies of a year or more.
- Portability. You can move to another insurer and carry your credits: no claim bonus, waiting periods already served, and the 60-month clock.
- Renewal can’t be refused for claiming. The insurer can’t deny renewal because you made a claim, and can’t re-check your health unless you raise the cover.
- Cashless in one hour. A cashless request must be decided within one hour, and discharge approval within three hours.
- The 60-month rule. After 60 months of continuous cover, a claim can’t be rejected for non-disclosure or misrepresentation, except for proven fraud. IRDAI calls this the moratorium.
The cover clock. Waiting periods start on day 1. IRDAI’s FAQs say no waiting period can run longer than 36 months. The 60-month clock runs on top. Both keep running only if your cover never breaks, which is why porting at renewal matters.
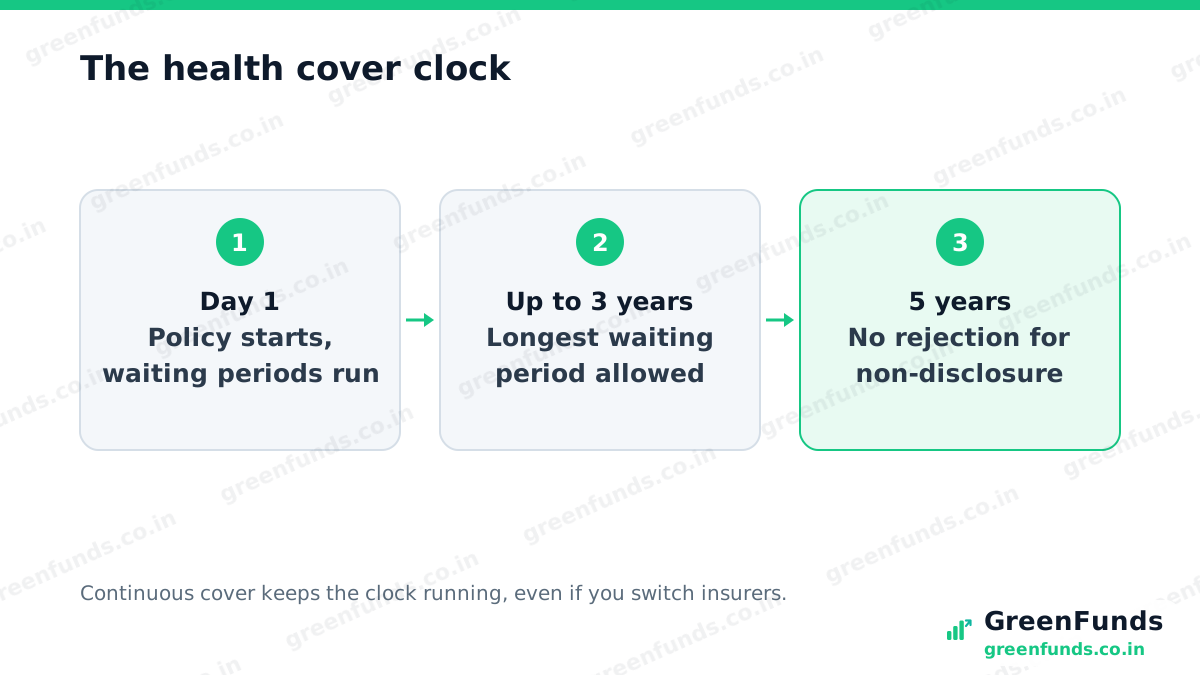
An illustration. Say Meera bought a policy at 28 and ported it at 31 (illustrative). Her three years carry over. At 33, she has five years of continuous cover. A claim now can’t be rejected because she forgot to mention an old condition, unless it was fraud.
Go deeper. Each of these has its own page:
- Super top-up health insurance: extra cover above a deductible, for less premium.
- Critical illness insurance: a lump sum on diagnosis, not a bill payment.
- How much health cover: a way to think it through for your city and family.
- The health insurance tax benefit: how premiums can lower your tax on the old regime.
- Health insurance for parents: the 2024 rules on age and waiting periods, and the parents’ tax bucket.
- Health insurance portability: how to switch insurers and keep your waiting-period credits.
- Ayushman Bharat PM-JAY: the government’s free cover, if your family is on the list or anyone is 70 or older.
The takeaway. Health insurance is simple at heart: a premium now, protection from a big bill later. Know your five rules, keep your cover continuous, and read the policy wording once, calmly. Rules get reviewed, so check the current version on irdai.gov.in.
Health cover pays hospital bills, not lost income after a disabling accident; that gap is what personal accident insurance covers.
More to read: term insurance, how much term cover, and why an emergency fund still matters alongside cover.
Questions people ask
What is health insurance in simple words?
You pay a yearly premium, and the insurer pays your covered hospital bills, up to a limit called the sum insured. It turns a bill that could cost lakhs into a known yearly cost.
Can I cancel a new health policy if I don't like it?
Yes. IRDAI gives you 30 days from the day you receive the policy document to review it and cancel, for policies with a term of one year or more. Your policy document says what, if anything, the insurer can keep from the refund.
Can I switch my health insurance to another insurer without losing waiting periods?
Yes, that is portability. When you port, the credits you built carry over to the new insurer, to the extent of your sum insured: no claim bonus, specific waiting periods, the pre-existing disease waiting period and the 60-month clock. Port at renewal so there is no break in cover.
Can an insurer reject my claim after many years for something I didn't disclose?
Not after 60 months of continuous cover. Per IRDAI's 2024 master circular, after that period no policy or claim can be contested for non-disclosure or misrepresentation, except for established fraud. Years under a ported or migrated policy count too.
How fast must an insurer decide on a cashless request?
Within one hour of receiving the request, and the final approval at discharge within three hours. If discharge approval runs past three hours, any extra amount the hospital charges must be borne by the insurer, per the 2024 master circular.
Source: IRDAI Master Circular on Health Insurance Business, 29 May 2024 (IRDAI/HLT/CIR/PRO/84/5/2024); IRDAI health insurance FAQs, irdai.gov.in/health-dept. Rules are reviewed often; check the current circular on irdai.gov.in.
Found this useful? You can buy us a coffee. It keeps GreenFunds free.Flag a possible issue
Was this helpful?
Thanks for the signal.
Comments
Share your experience or a question. Be kind, stay on topic. This is reader discussion, not financial advice.
No comments yet. Be the first to share.