Super top-up health insurance: top-up vs super top-up, with a rupee example
Extra health cover that pays only after your bills cross a set amount
A top-up is extra health cover that pays only after your bills cross a set amount, called the deductible. Because the insurer skips the first part of every claim, the premium is usually far lower than raising your base sum insured. A super top-up works the same way, with one big difference.
The deductible, in simple words. The standard definition in policy wordings says the insurer won’t pay a specified rupee amount before benefits start. It doesn’t reduce your sum insured. So a 20 lakh top-up above a 5 lakh deductible can pay up to 20 lakh, but only once you cross 5 lakh.
Top-up vs super top-up. The question is how the deductible is counted.
- Top-up: usually checks each hospital bill alone. A bill pays out only if that single bill crosses the deductible.
- Super top-up: usually adds up all your bills in the policy year. Once the total crosses the deductible, it pays.
That one change matters when a year brings two or three medium bills instead of one big one.
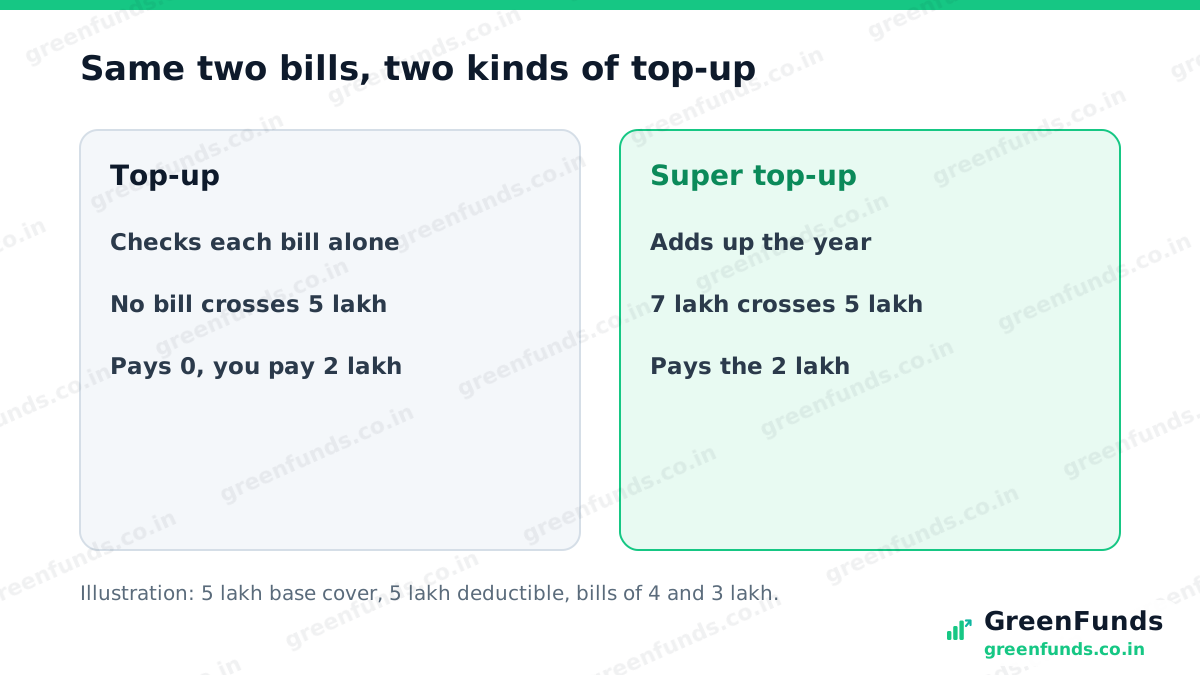
A rupee illustration. Say you have a 5 lakh base policy and a top-up with a 5 lakh deductible (illustrative numbers). This year brings two hospital stays: 4 lakh, then 3 lakh. Total: 7 lakh.
- Your base policy pays the first 5 lakh. 2 lakh is left.
- A top-up checks each bill. Neither 4 lakh nor 3 lakh crosses 5 lakh. It pays nothing. You pay 2 lakh.
- A super top-up adds up the year. 7 lakh crosses 5 lakh. It pays the 2 lakh.
Read the wording, not the name. Product names aren’t standard. Some policies sold as “top-up” count the deductible across the whole year, like a super top-up. Find the line that says how the deductible applies: per claim, or on the aggregate of claims in a year.
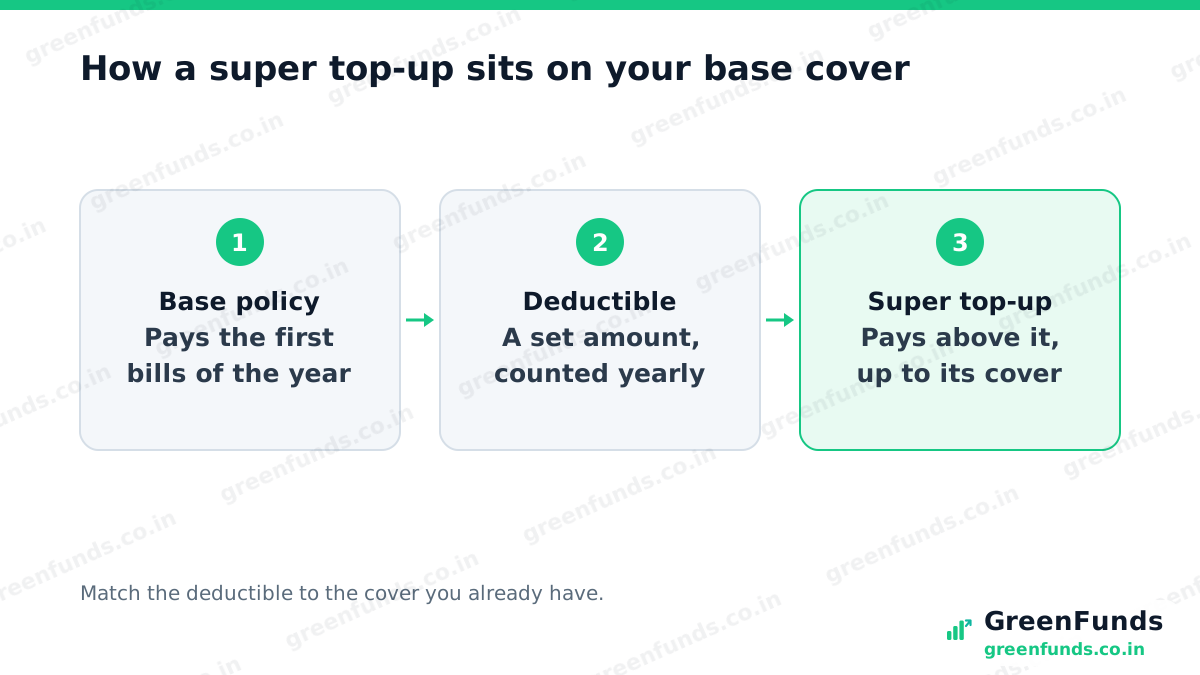
How the layers fit. Your base policy pays first. The deductible is usually set to match it. Above that, the super top-up takes over, up to its own cover. If the deductible is higher than your base cover, the gap comes out of your pocket.
Claiming from two policies. Under IRDAI’s 2024 master circular, you choose which policy to claim first. If it falls short, that insurer coordinates with your other insurers for the balance. Keep copies of every bill, since the second insurer will want them.
Before you buy, check:
- Is the deductible per claim or per year?
- Does it match your base or employer cover?
- Do the same waiting periods, room rent limit and co-pay rules apply?
- Is it a family floater, sharing one cover across members?
The takeaway. A super top-up buys a big layer of cover cheaply, by skipping the bills your base policy already pays. Count how the deductible works in rupees before you rely on it.
More to read: our health insurance guide, how much health cover to think about, and cashless vs reimbursement claims.
Questions people ask
What is the difference between top-up and super top-up health insurance?
Both pay only above a deductible. A top-up usually checks each hospital bill alone, so it pays only when a single bill crosses the deductible. A super top-up usually adds up all bills in the policy year, so several smaller bills can cross it together. Product names are not a rule, so read how your wording applies the deductible.
Do I need a base health policy to buy a super top-up?
Not always, but without one you pay every bill up to the deductible yourself. Most people pair a super top-up with a base policy, an employer policy, or both, so the deductible is already covered.
What is a deductible in health insurance?
It is a set rupee amount the insurer won't pay, which applies before the policy pays anything. In the standard definition used in policy wordings, a deductible does not reduce the sum insured.
Can I claim from my base policy and super top-up for the same hospital stay?
Yes. Under IRDAI's 2024 master circular, you choose which policy to claim first. If that cover falls short, the primary insurer coordinates with your other insurers for the balance, as per their terms.
Source: IRDAI standard definition of deductible, as used in health policy wordings filed with IRDAI (irdai.gov.in); IRDAI Master Circular on Health Insurance Business, 29 May 2024 (claims under multiple policies). How the deductible applies varies by product; check the policy wording.
Found this useful? You can buy us a coffee. It keeps GreenFunds free.Flag a possible issue
Was this helpful?
Thanks for the signal.
Comments
Share your experience or a question. Be kind, stay on topic. This is reader discussion, not financial advice.
No comments yet. Be the first to share.