Money after marriage: accounts, nominees and shared goals
Talk first, then set up the accounts, and update every nominee
Figures checked 2026-11-01
Marriage doesn’t come with a money manual. Two people, two incomes, two sets of habits and maybe two sets of loans now share one life. Getting it right is less about investing and more about three simple things: talking openly, setting up accounts that suit you both, and updating who gets your money if something happens.
Start with one honest conversation. Before any account opens, share the real numbers: what each of you earns, owes and spends, and what you’re saving for. Debts matter most. A credit card balance or a personal loan doesn’t disappear on marriage, and hiding one causes more trouble than the debt itself.
Choose an account setup. Couples usually pick one of three:
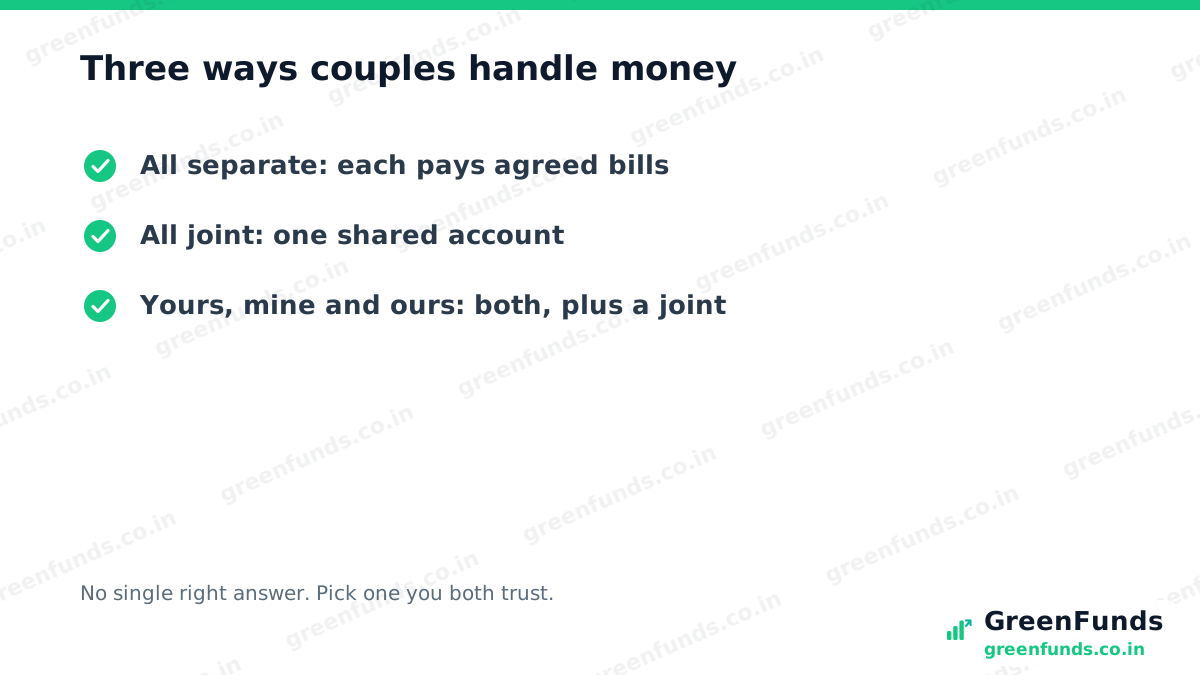
A joint account is handy for rent, groceries and bills. Splitting shared costs by income can feel fairer than 50-50. Say shared costs are 50,000 rupees a month and one of you earns 60% of the household income (an illustration): that person puts in 30,000 rupees, and the other puts in 20,000. Our explainer on couples financial planning goes deeper on splitting costs and shared tax questions.
Update every nominee. This is the step most couples forget, and it’s the one with legal teeth.
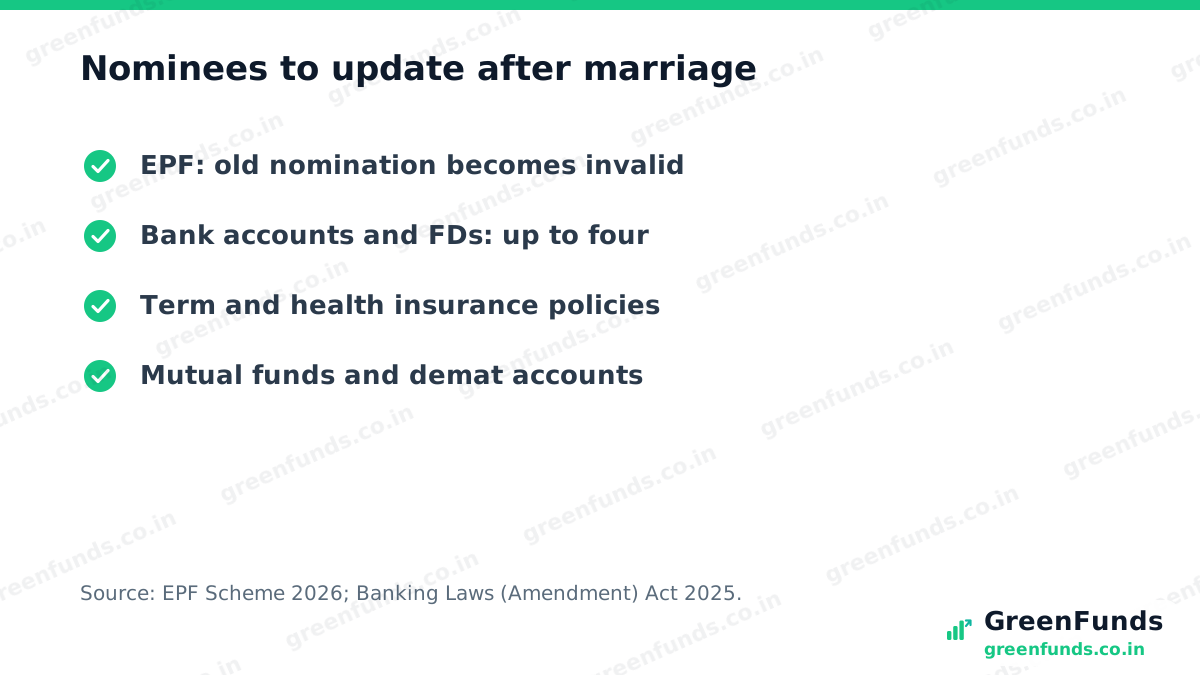
Did you know? Under the Employees’ Provident Funds Scheme, 2026, any EPF nomination you made before marriage is automatically treated as invalid, and you must file a fresh one. If you have a family, the nominee must be a family member. And since November 2025, a bank deposit can have up to four nominees, per the Finance Ministry.
Our lesson on nomination explains how nominees work across accounts. If either of you has people depending on your income, this is also the moment to look at term insurance, and to make sure health cover includes your spouse.
Plan shared goals. A home, a child, a trip, retirement: write them down with a rough amount and a date. Then match each to the right kind of saving using the time-horizon method in our money goals lesson. Keep one shared emergency fund too, since one income may need to carry both of you for a while.
A safety note on joint deposits. Bank deposit insurance covers up to 5 lakh rupees per depositor per bank, and DICGC treats a joint account as a separate holding from each person’s own account. Our explainer on deposit insurance shows how it’s counted.
The takeaway. Talk numbers first, pick an account setup you both trust, and update every nominee, starting with your EPF, which marriage resets automatically. The investing decisions come easier once those basics are in place.
More to read: planning for a baby, if you lose your job, and the EPF withdrawal rules.
Questions people ask
Should a married couple have a joint bank account?
There's no single right answer. Many couples keep their own accounts and add one joint account for shared bills and goals. A joint account is convenient, but both holders can usually operate it, so it works best when you trust each other's spending and agree on what it's for.
Do I need to change my EPF nominee after marriage?
Yes. Under the Employees' Provident Funds Scheme, 2026, any EPF nomination made before marriage is deemed invalid, and a fresh one must be made. If you have a family, the nominee must be a family member. You can update it online through EPFO's e-nomination facility.
How many nominees can I add to a bank account?
Up to four. Since 1 November 2025, the Banking Laws (Amendment) Act, 2025 lets you name up to four nominees for a deposit account, either together with set percentages or one after another, per the Finance Ministry.
Should we combine all our money after marriage?
Not necessarily. A common setup is yours, mine and ours: each keeps a personal account, and both put an agreed amount into a shared one for rent, bills and joint goals. What matters more is that you both know the numbers, the debts and the plan.
Sources
- Employees' Provident Funds Scheme, 2026 (G.S.R. 525(E), 29 June 2026), paragraph 44 A fresh nomination must be made on marriage, and any nomination made before marriage is deemed invalid; nominations under the 1952 scheme are void to the extent inconsistent with the 2026 scheme.
- PIB, nomination provisions of the Banking Laws (Amendment) Act, 2025 effective from 1 November 2025 Up to four nominees for deposit accounts, simultaneous with set shares totalling 100%, or successive.
- DICGC, FAQs Deposits held in different capacities, such as a joint account, are insured separately up to 5 lakh rupees.