Home insurance basics: covering the building and what's inside
A home policy pays to rebuild your home and replace your belongings after fire or disaster
Figures checked 2026-11-01
Home insurance pays to repair or rebuild your home, and replace what’s inside it, after a fire or another disaster the policy lists. You can cover the building if you own it, just your belongings if you rent, or both. For most families, a home is the biggest thing they own and the one they’re least likely to have insured.
Two things you can cover. IRDAI’s 2024 Master Circular says a homeowner policy covers the building, if it’s yours, and/or your contents and personal belongings: clothes, gadgets, the TV, fridge and washing machine, furniture, fans and lights, and kitchen and bathroom fittings. A tenant can insure only the contents.
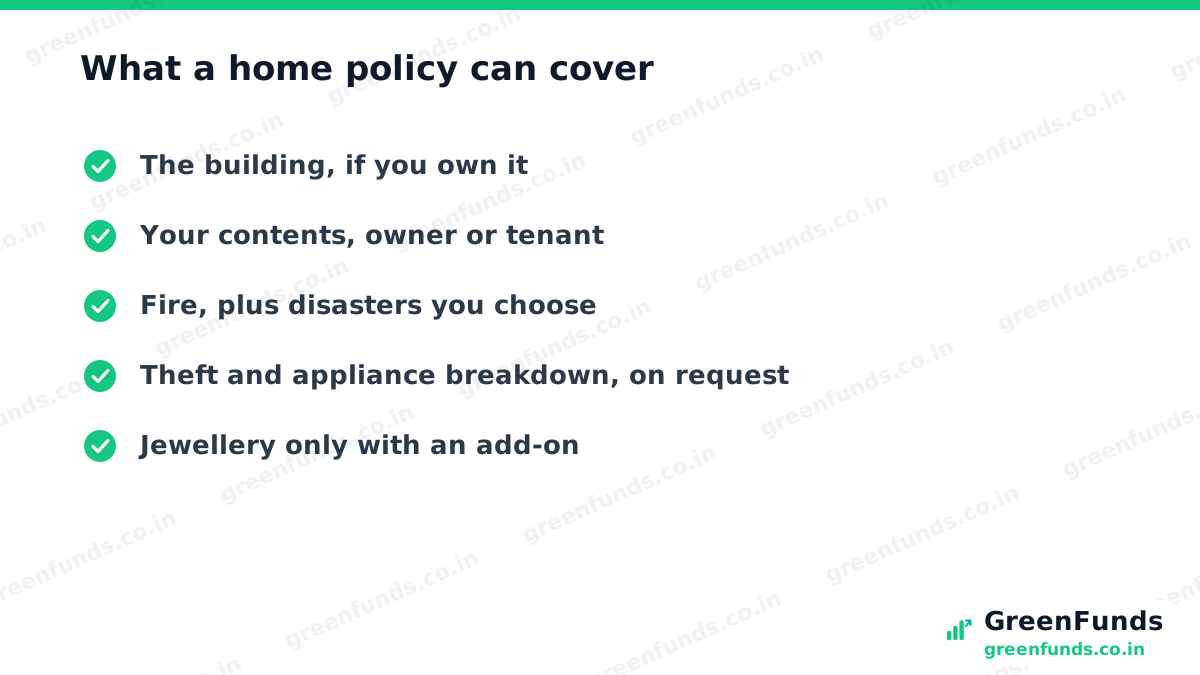
Which disasters. Fire is the base cover. You can then include, or leave out, earthquake, cyclone and storm, flood, lightning, landslide, and the explosion of a domestic pressure vessel like a cooker or geyser. The idea is to match your area: earthquake cover in a seismic zone, cyclone cover on the coast, flood cover near a river. You can also ask to add burglary and theft of contents, and electrical breakdown of appliances.
The standard policy. IRDAI created a standard home policy, Bharat Griha Raksha, to replace the old fire policy for homes. In its standard wording, your general contents are covered automatically at 20% of the building’s sum insured, up to 10 lakh rupees, unless you opt out or declare a higher value. So a home insured for 20 lakh rupees comes with 4 lakh of contents cover built in (an illustration). Jewellery and other valuables are not included unless you buy the optional valuables cover.
Did you know? IRDAI’s 2024 rules say no warranties apply to homeowners’ policies, so a claim can’t be turned down over a technical condition that had nothing to do with the loss. And the insurer can’t reject a claim just because you reported it late, if the delay didn’t make the loss bigger.
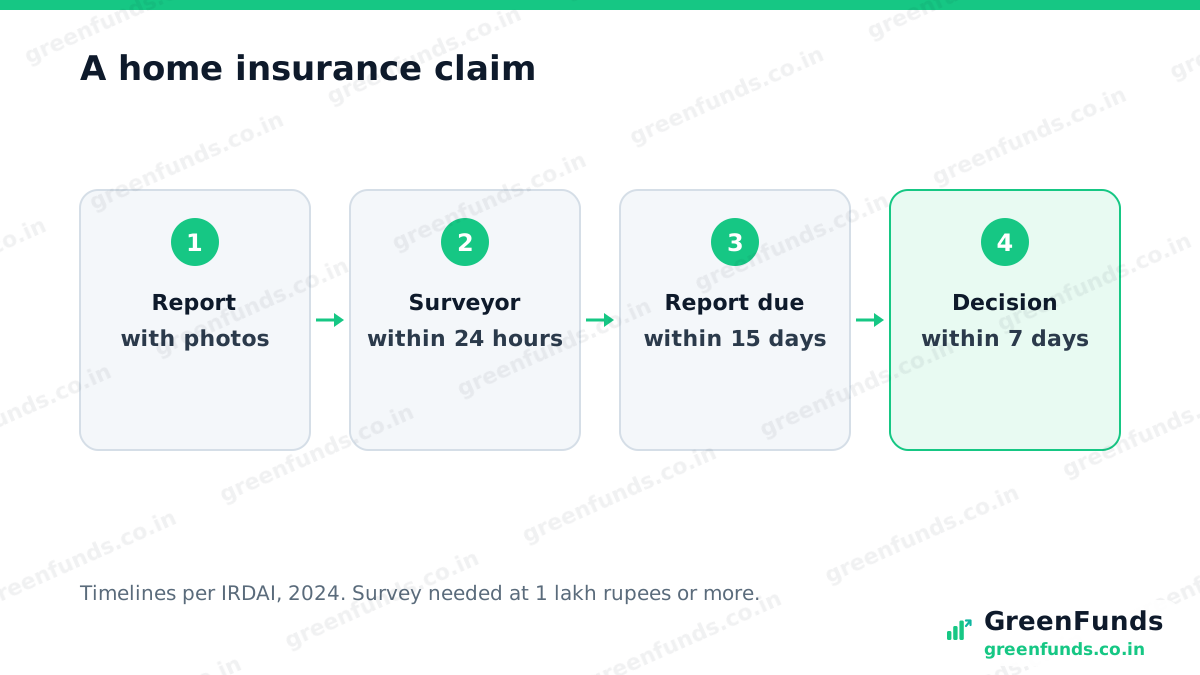
How a claim works. Report the loss to your insurer quickly, with photos and bills where you have them. For losses of 1 lakh rupees or more, a registered surveyor must assess the damage.
The takeaway. A home policy protects the one asset most families can’t replace from savings. Cover the building if you own it, your contents either way, pick the disasters that fit where you live, and add a valuables cover if you keep jewellery at home.
More to read: how insurance works, the emergency fund, and bank locker rules if you keep valuables outside the house.
Questions people ask
Can I get home insurance if I rent?
Yes. IRDAI's 2024 Master Circular says a homeowner policy can cover the building if you own it, and/or your contents and personal belongings, such as clothes, gadgets, appliances, furniture, fixtures and fittings. A tenant can insure just the contents.
Does home insurance cover theft and earthquakes?
Fire is the base cover. IRDAI's rules let you add or remove perils such as earthquake, cyclone and storm, flood, lightning, landslide and explosion of domestic pressure vessels. Burglary or theft of contents, and electrical breakdown of appliances, can be added on request.
What is Bharat Griha Raksha?
It is IRDAI's standard home policy, introduced to replace the old fire policy for dwellings. In IRDAI's standard wording, general contents are covered automatically at 20% of the building's sum insured, up to 10 lakh rupees, unless you opt out or declare a higher value. Jewellery and valuables need a separate optional cover.
How quickly must a home insurance claim be settled?
Per IRDAI's 2024 Master Circular, a surveyor should be allocated within 24 hours, the survey report is due within 15 days, and the insurer must decide within 7 days of the report. Losses of 1 lakh rupees or more outside motor insurance must be surveyed by a registered surveyor.
Sources
- IRDAI, Master Circular on Protection of Policyholders' Interests, 2024 Homeowner (fire) insurance covers the building (if owned) and/or contents and personal belongings; option to include or exclude earthquake, cyclone/storm, flood, lightning, landslide and explosion of domestic pressure vessels; burglary/theft and electrical damage on request; no warranties on homeowners products. Claims: surveyor within 24 hours, report within 15 days, decision within 7 days; mandatory survey for non-motor losses of Rs 1 lakh or more.
- IRDAI, standard Bharat Griha Raksha policy wording (Annexure I) General contents covered automatically at 20% of the home building sum insured, up to Rs 10 lakh, unless opted out or a higher value is declared; jewellery and valuables only under the optional valuable contents cover.