Jan Dhan account: benefits, RuPay accident cover, overdraft and how to open
A Jan Dhan account is a zero-balance basic savings account with a free RuPay card, accident cover and a small overdraft
Pradhan Mantri Jan Dhan Yojana, or PMJDY, began on 28 August 2014 to give every unbanked adult a bank account. It is a basic savings account with no minimum balance, a free card and a few protections built in. The government’s 27 August 2026 release counted 59.09 crore Jan Dhan accounts holding 3.17 lakh crore rupees, as on 19 August 2026.
What you get
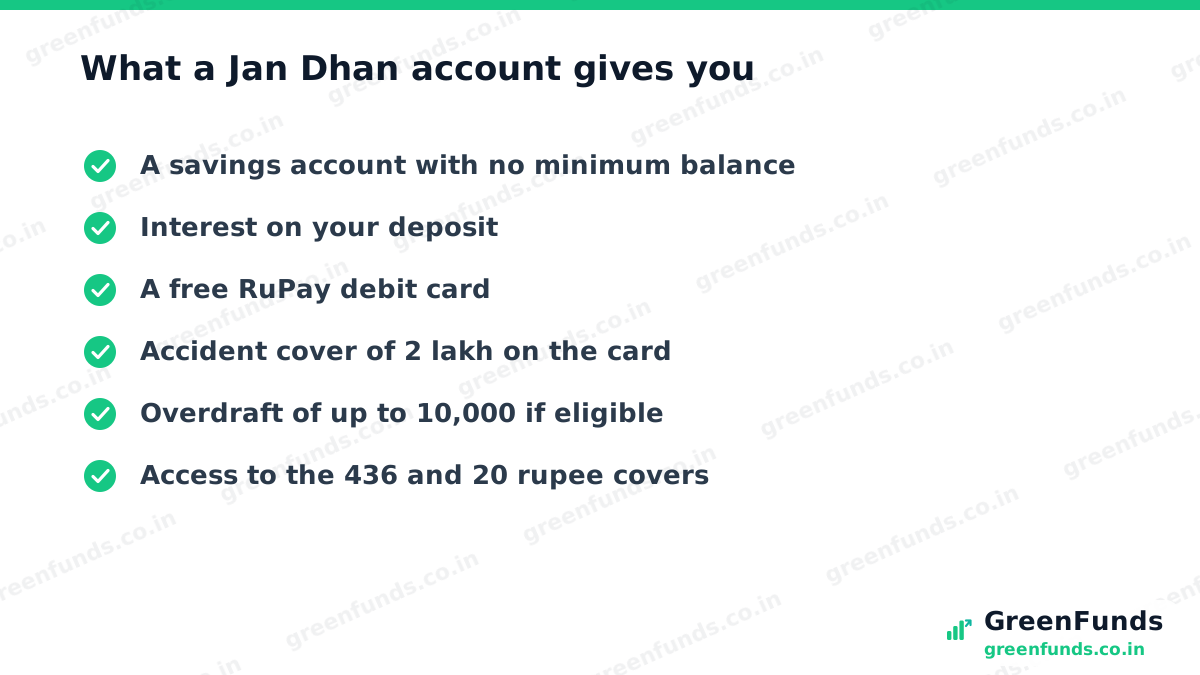
- Zero balance. A Jan Dhan account is a BSBDA, so there is no minimum balance and no charge for a low one. You earn interest on your deposit.
- Free RuPay card. A debit card for ATMs, shops and online payments.
- Accident cover on the card. 2 lakh rupees for accidental death or permanent total disability, or 1 lakh rupees if the account was opened before 28 August 2018.
- Overdraft. Up to 10,000 rupees for eligible holders. An overdraft lets you withdraw more than your balance, as a short loan.
- Links to other schemes. Direct benefit transfers, PMJJBY, PMSBY, Atal Pension Yojana and MUDRA loans.
The conditions to know
The card cover needs an active card. The RuPay insurance FAQ on pmjdy.gov.in (FY 2016-17, the latest posted) pays a claim only if the cardholder made at least one successful transaction within 90 days before the accident, for a regular card. Any channel counts: ATM, shop, online or a Bank Mitra. An unused card can leave a family with nothing.
The overdraft is a loan. The 2018 changes raised the limit from 5,000 to 10,000 rupees, removed conditions for amounts up to 2,000 rupees, and set the age limit at 18 to 65. Beyond 2,000 rupees, conditions apply. You repay with interest.
How to open one
Go to any bank branch or a Bank Mitra (business correspondent) outlet. Fill the form and complete KYC, usually with Aadhaar. The scheme is meant for people who do not already have a bank account. If you have no official documents, the bank can open a small account. It lasts 12 months, and another 12 if you show you have applied for an official document.
Adding life and accident cover
A Jan Dhan account is also the cheapest gateway to insurance. Through it you can join PMJJBY for life cover and PMSBY for accident cover, by auto-debit.
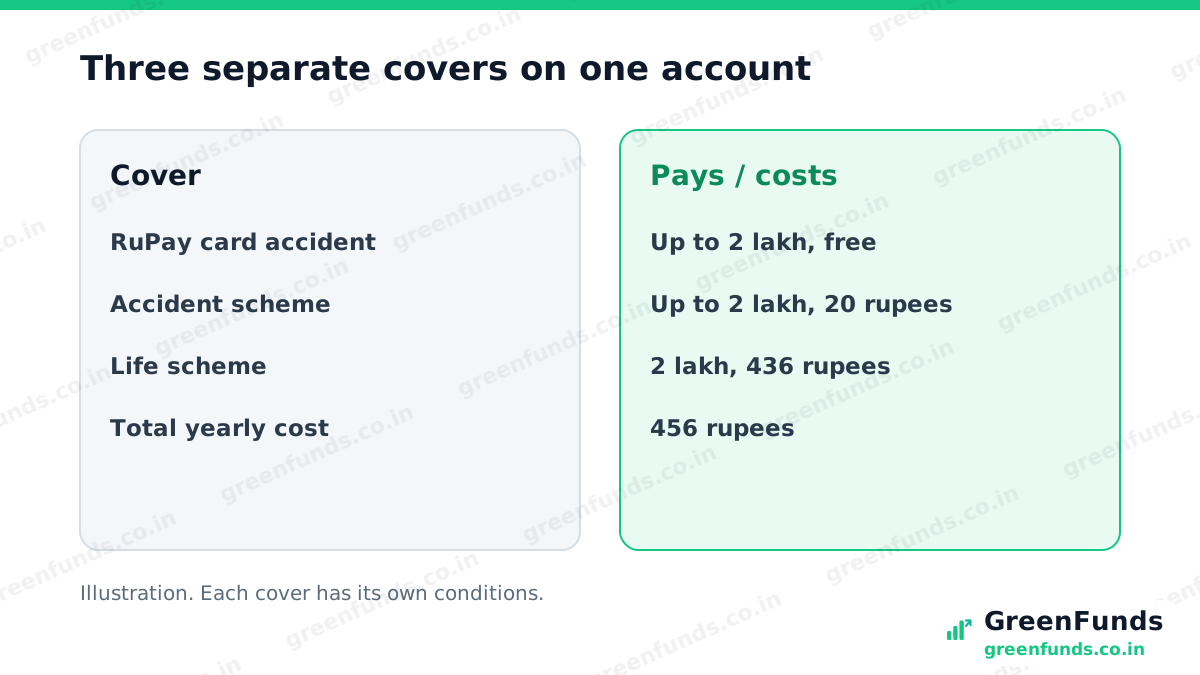
An illustration. Ravi, 30, opened his Jan Dhan account in 2020 and joins both schemes. He pays 436 plus 20, so 456 rupees a year. If he died in an accident while all three covers were active and his card had been used within 90 days, his nominee could claim 2 lakh rupees from each, up to 6 lakh rupees in all. For illness, only PMJJBY would pay, so 2 lakh rupees.
Did you know? About 56% of Jan Dhan account holders are women, and 78% of accounts are in rural and semi-urban areas, according to the government’s August 2026 figures.
The takeaway. A Jan Dhan account costs nothing to keep and opens the door to cheap insurance. Use the card now and then so its accident cover stays live, and add PMJJBY and PMSBY. Health cover is separate: check if your family qualifies for Ayushman Bharat PM-JAY.
More to read: deposit insurance up to 5 lakh, post office schemes, and Atal Pension Yojana.
Questions people ask
What are the benefits of a PM Jan Dhan account?
No minimum balance, interest on your deposit, a free RuPay debit card with accident cover of 2 lakh rupees (1 lakh rupees for accounts opened before 28 August 2018), an overdraft of up to 10,000 rupees for eligible holders, and eligibility for direct benefit transfers, PMJJBY, PMSBY, Atal Pension Yojana and MUDRA loans.
Is a Jan Dhan account zero balance?
Yes. It is a basic savings bank deposit account, so there is no minimum balance to keep and no charge for a low balance. You still earn interest on what you deposit.
How does the Jan Dhan overdraft work?
Eligible account holders can get an overdraft of up to 10,000 rupees. Under the 2018 changes to the scheme, there are no conditions attached for an overdraft of up to 2,000 rupees, and the age limit for the overdraft is 18 to 65. It is a loan, so you repay it with interest.
How do I open a Jan Dhan account?
Visit any bank branch or a Bank Mitra (business correspondent) outlet, fill the account opening form and complete KYC, usually with Aadhaar. The scheme is meant for people who do not already have a bank account. If you have no official documents, the bank can open a small account, valid for 12 months and extendable by 12 more if you show you have applied for one.
Does the RuPay card accident cover need the card to be used?
Yes. The RuPay insurance FAQ posted on pmjdy.gov.in (for FY 2016-17) pays only if the cardholder made at least one successful transaction, by any channel, within 90 days before the accident for a regular card. Using the card or account now and then keeps the cover alive.
Source: Department of Financial Services, PMJDY scheme details (pmjdy.gov.in) and 'Continuation of PMJDY' note, 2018 (pmjdy.gov.in); PIB release 'PM Jan Dhan Yojana completes 12 years', 27 August 2026 (ID 2303643); PIB backgrounder '11 Years of PM Jan Dhan Yojana', 27 August 2025; DFS Annual Report 2025-26, section 6.1; RuPay Insurance Program FAQ, FY 2016-17 (pmjdy.gov.in).
Found this useful? You can buy us a coffee. It keeps GreenFunds free.Flag a possible issue
Was this helpful?
Thanks for the signal.
Comments
Share your experience or a question. Be kind, stay on topic. This is reader discussion, not financial advice.
No comments yet. Be the first to share.