Gold loans: the real cost, and RBI's new rules
A gold loan is cheap and quick, but the limit, repayment type and auction risk decide its real cost
A gold loan lets you borrow against your jewellery without selling it. The lender holds the gold until you repay. It’s quick and easy to get, but how much you can borrow, and what happens if you can’t repay, now follow stricter RBI rules.
What happened. Gold loans have boomed. By 30 June 2026, Indians owed banks about ₹5.36 lakh crore against gold jewellery, up about 16% in just three months, per provisional RBI data. RBI’s new rules for these loans, issued in June 2025, apply to banks and lending companies from 1 April 2026.
Why it matters to you. If a family emergency or a business gap has you eyeing the gold at home, these rules decide how much cash you get, how you repay, and how safe your jewellery is.
How much you can borrow. The share of your gold’s value you can borrow is the loan-to-value limit, or LTV. RBI caps it by loan size: 85% for loans up to ₹2.5 lakh, 80% up to ₹5 lakh, and 75% above that. Only the gold counts, not stones, and the lender uses the lower of the previous day’s price and the 30-day average.
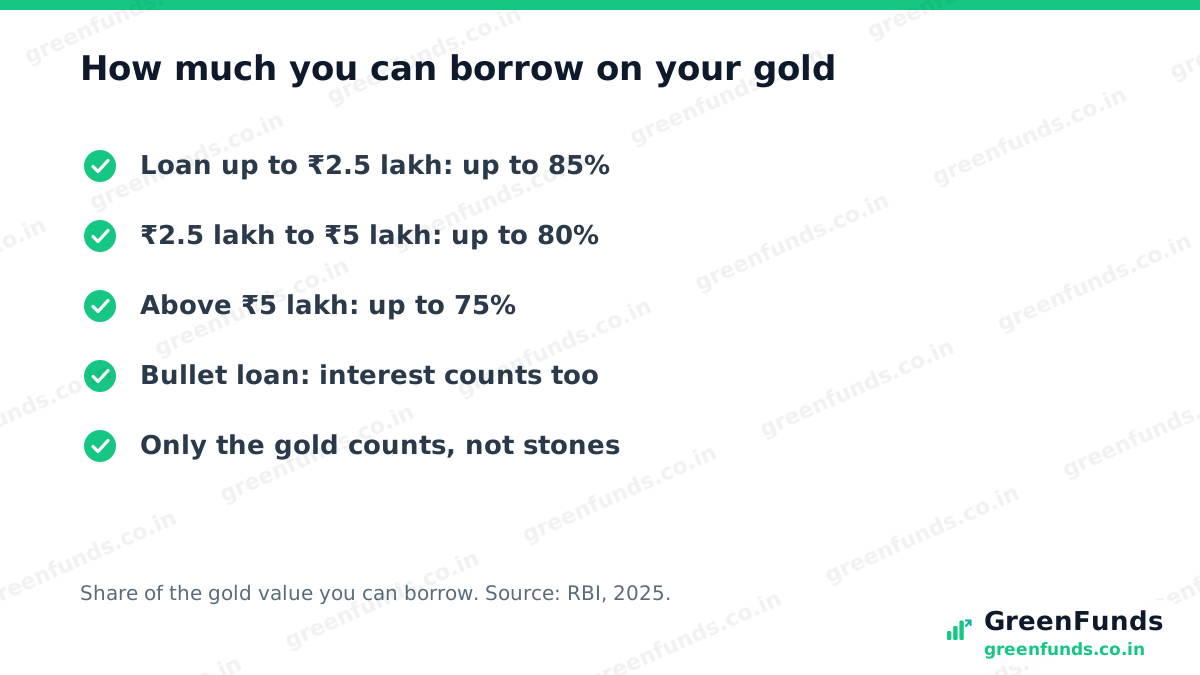
The bullet loan catch. Many gold loans are “bullet” loans: you pay nothing monthly, then repay everything at the end. RBI caps these at 12 months for personal needs. And the interest due at the end must also fit inside the limit, so you get less cash upfront.
In rupees. Take jewellery with ₹2 lakh of gold in it. The 85% limit is ₹1.7 lakh. On a 12-month bullet loan at an illustrative 12% a year, principal plus interest must stay within ₹1.7 lakh. So you can borrow only about ₹1.52 lakh, and repay about ₹1.7 lakh at the end. With a monthly EMI loan, the full ₹1.7 lakh can be the principal.
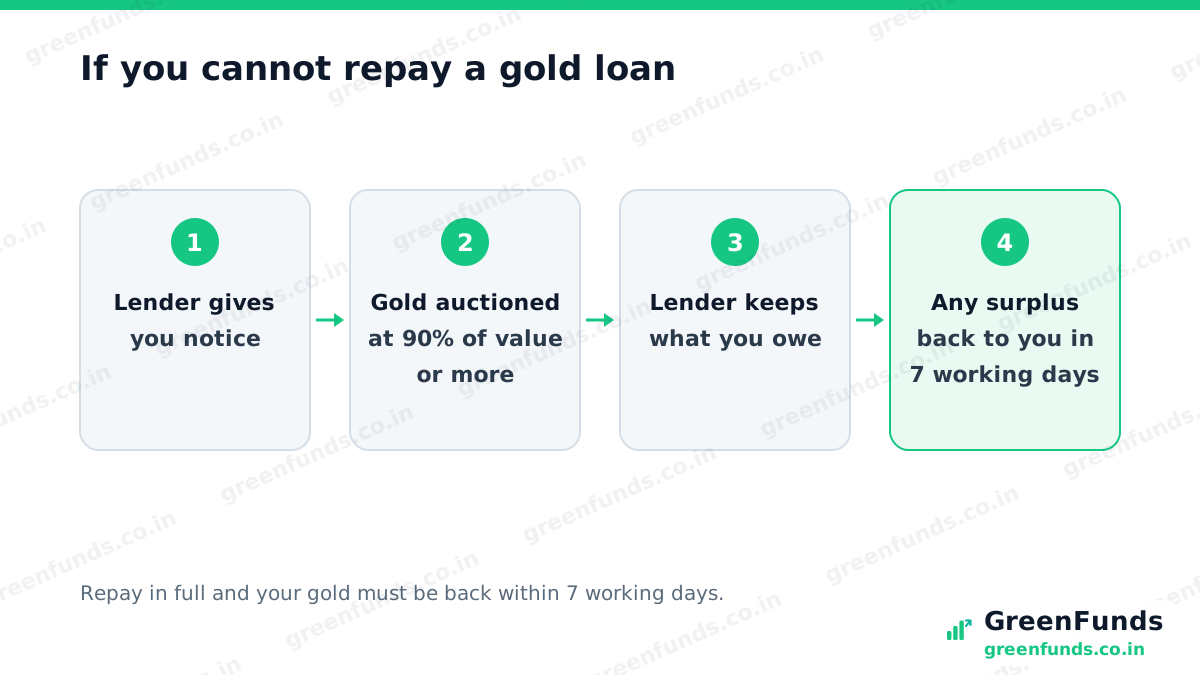
Getting your gold back. Repay in full, and the lender must return your gold the same day, or within seven working days at most. If it’s late through its own fault, it owes you ₹5,000 for every day of delay. All terms must be shared in your region’s language or one you choose.
If you can’t repay. The lender must give you notice before any auction. The reserve price must be at least 90% of the gold’s current value, or 85% after two failed auctions. It keeps what you owe, and must refund any surplus within seven working days.
Before you pledge. Borrow only from a bank or an RBI-regulated lender, and read the valuation, all charges and the auction terms in writing. Borrow well below the limit, so a dip in gold prices doesn’t squeeze you. And plan the repayment before you sign: family jewellery is hard to replace once it is auctioned.
More to read: personal loan vs credit card, should you prepay a loan, and how your credit score works.
Questions people ask
How much gold loan can I get?
Under RBI rules, up to 85% of your gold's value for loans up to 2.5 lakh rupees, 80% for loans above 2.5 lakh up to 5 lakh, and 75% above 5 lakh. Only the gold itself counts, not stones or other materials, and it is valued at the lower of the previous day's price and the 30-day average.
What is a bullet repayment gold loan?
A loan where you pay nothing until the end, then repay the principal and all the interest in one go. RBI caps these at 12 months for personal needs, and the interest due at the end counts inside the borrowing limit.
How soon must the lender return my gold?
The same day you repay in full, and no later than seven working days. If the lender is at fault for a longer delay, it must pay you 5,000 rupees for each day of delay.
Is a gold loan better than a personal loan?
It is often easier to get, because the gold secures it, so lenders may lean less on your credit score. But you put your jewellery at risk: if you cannot repay, it can be auctioned. Compare the full cost and charges, and borrow only what you can repay on time.
Source: RBI (Lending Against Gold and Silver Collateral) Directions, 6 June 2025, applied by 1 April 2026, now part of RBI's Credit Facilities and Responsible Business Conduct Directions, 2025; RBI Bulletin, sectoral deployment of bank credit, 30 June 2026 (provisional). Rules change, check rbi.org.in.
Found this useful? You can buy us a coffee. It keeps GreenFunds free.Flag a possible issue
Was this helpful?
Thanks for the signal.
Comments
Share your experience or a question. Be kind, stay on topic. This is reader discussion, not financial advice.
No comments yet. Be the first to share.