The fund that can pay you back the same day
Liquid funds and the instant access facility
What a liquid fund is. A mutual fund holding debt that matures within 91 days. Because the holdings turn over so fast, the value barely moves when interest rates change. It is built for money you may need soon, not money you want to grow.
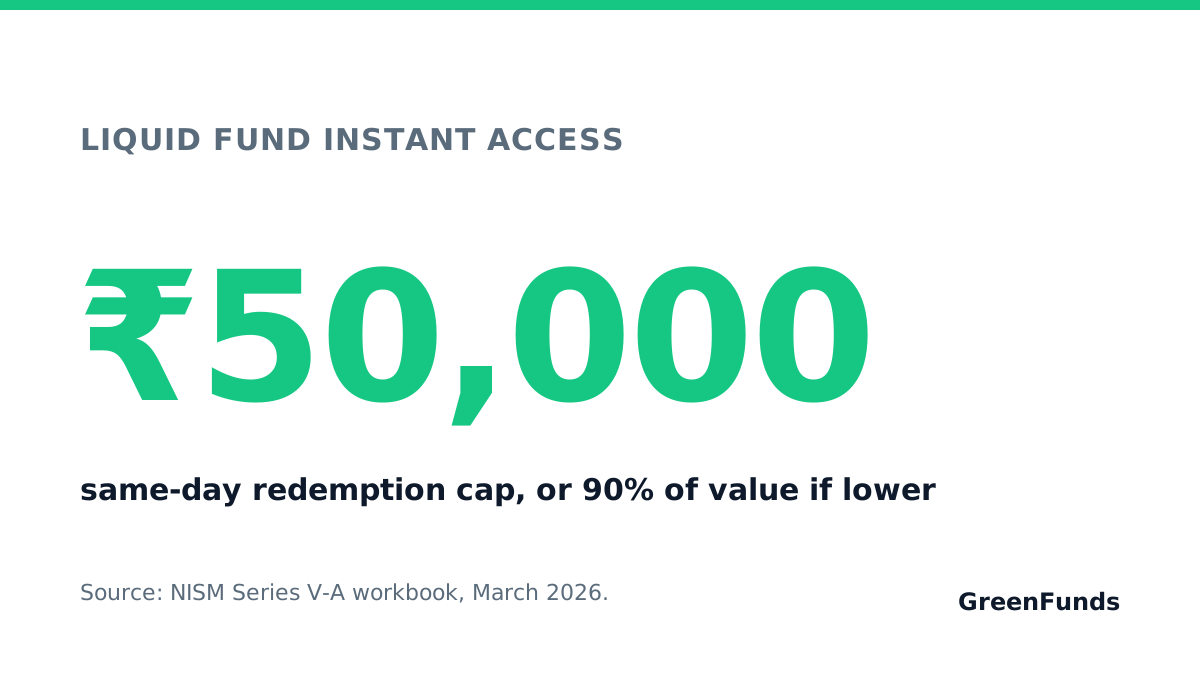
The same-day part. Some liquid schemes offer an instant access facility, which credits redemption money to your bank on the same day. The cap is ₹50,000 or 90 percent of your value in that scheme, whichever is lower, per day, per scheme, per investor.
A rupee example. You hold ₹40,000 in such a scheme. Ninety percent of that is ₹36,000, which is below ₹50,000, so ₹36,000 is what you can pull the same day. The rest follows on the normal cycle.
The honest caveat. Low risk is not no risk. A liquid fund can still be hit by a credit problem in what it holds, and in 2018 and 2019 several were. Low risk means the interest rate risk is small, not that nothing can go wrong.
Plenty of people keep one month of expenses in a savings account for instant reach and the rest of their cushion here.
How it compares with a savings account. A savings account is instant, at any hour, with no cap and no paperwork. A liquid fund usually pays a little more and normally credits the next working day. Neither is better. They are different jobs.
What to check before relying on it. Not every liquid scheme offers instant access, so confirm yours does before you count on it. Check how the fund house actually processes the request out of hours, and remember any returns you earn here are taxable.
A sensible split. Many people keep about one month of expenses in a savings account for instant reach and the rest of the cushion in a liquid fund. You get same-hour access to the part you are most likely to need and slightly better returns on the part you probably will not touch.
This is general education, not financial advice. Figures are as reported by the source and may change.
Source: NISM Series V-A workbook, March 2026 edition.
Ready to try your first ₹100? Open a free account.
Compare beginner friendly investing apps and open an account in a few minutes.
Compare apps →