Your credit score, explained: the number behind every loan
A higher score means cheaper credit
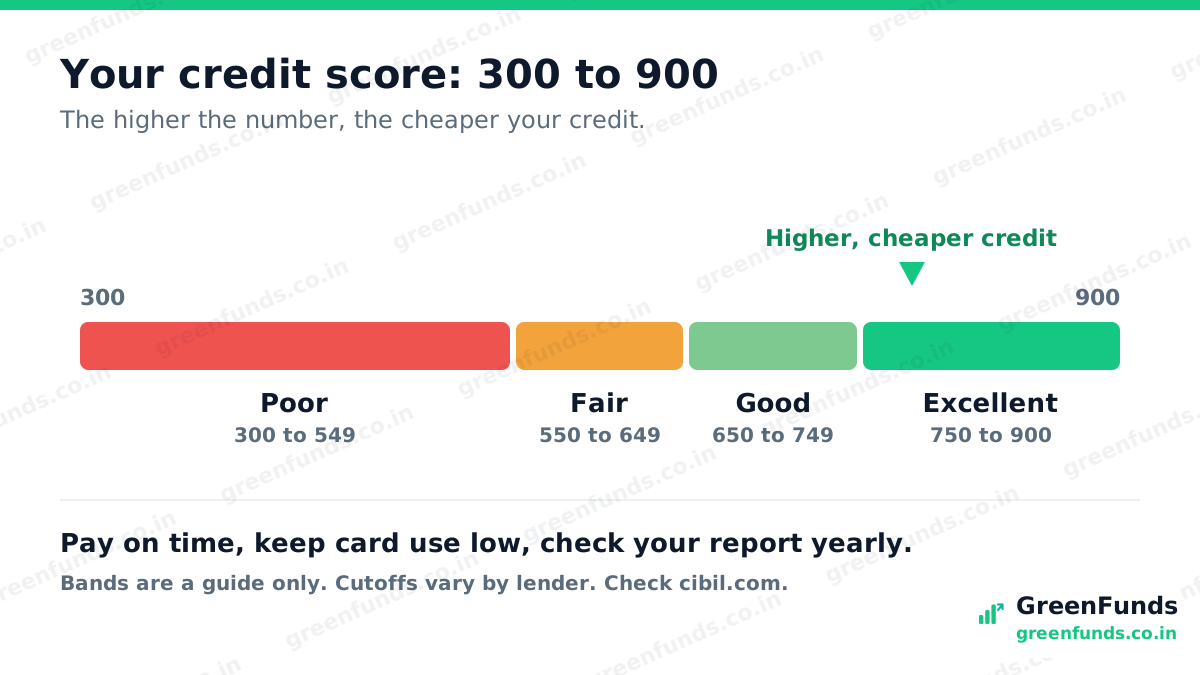
What it is. Your credit score is a three digit number, from 300 to 900, that lenders check before they give you a loan or a credit card. Credit bureaus build it from your repayment record. CIBIL is the best known, and Experian, Equifax and CRIF High Mark keep their own. A higher number tells a lender you repay on time. CIBIL does not publish its exact formula, so treat any precise “weightage” you see online as an estimate.
Why it matters to you. A strong score does two things: it makes approval easier, and it can get you a lower interest rate. A weak score can mean a flat rejection, or a loan that costs you more every month for years.
What a lower rate is worth. Rate is where the score pays off. Take a ₹5 lakh personal loan over five years. At 14% a year the EMI is about ₹11,600 a month. At 18% it is about ₹12,700. That is roughly ₹60,000 more over the loan, for the exact same borrowing. The better your score, the better the rate a lender is likely to offer. Illustration only; your actual rate depends on the lender.
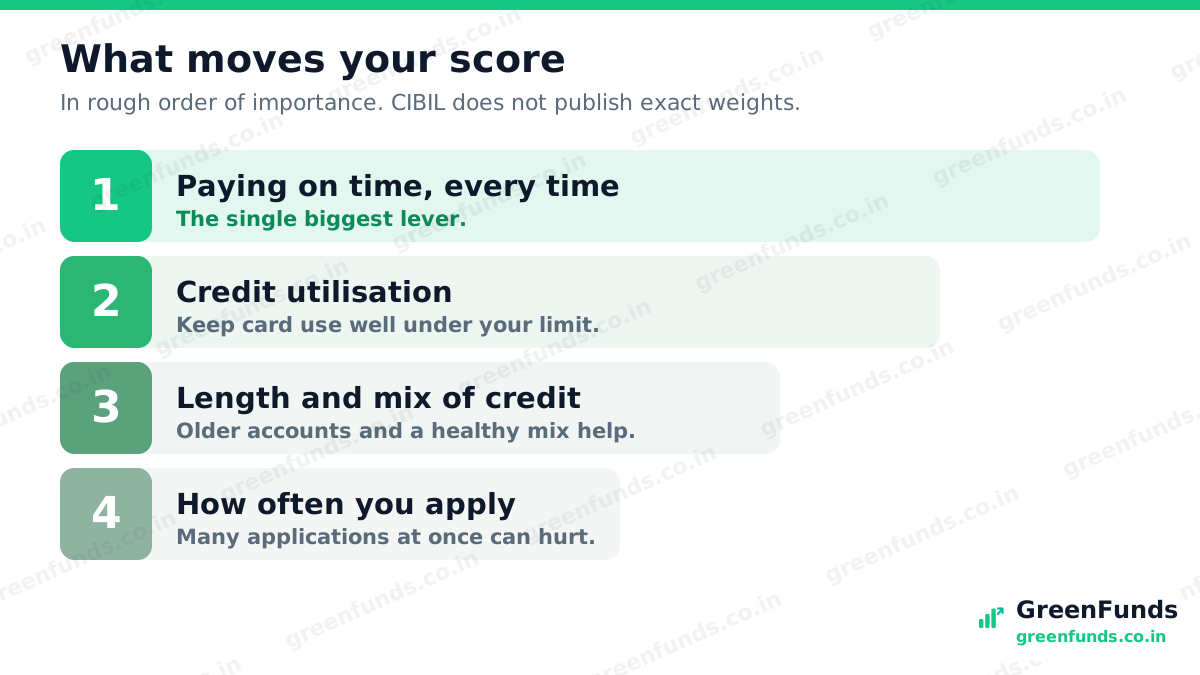
What moves your score. In rough order of importance:
- Paying on time, every time. This is the single biggest lever. One missed card or EMI payment can pull your score down fast.
- Credit utilisation. How much of your card limit you use. Keeping it low, well under the limit, helps.
- A long, healthy history. Older accounts and a sensible mix of credit count in your favour.
- How often you apply. Many loan or card applications in a short time can each leave a mark and dent the score.
CIBIL keeps the exact weights private, so think of these as levers, not a formula.
A good score, roughly. Many lenders treat a higher score, often around 750 and above, as strong. But there is no single official cutoff, and it varies by lender and product. Aim high rather than at a magic number.
Checking your own score does not hurt it. When you check your own score it is a soft enquiry and changes nothing. Only a hard enquiry, when a lender checks because you applied, can nudge it. So check yours often.
How to see yours, free. RBI has required each credit bureau to give you one free full credit report a year, and many banks and apps show a score for free too. Pull your report, read it, and if you spot a loan or default that is not yours, raise a dispute with the bureau. Errors are common, and they cost you. Confirm the current free-report process on the bureau’s own site.
The habits that build it. Pay your full card bill by the due date, not just the minimum due. Keep your card usage low. Do not chase every new card offer. Keep your oldest account open. And check your report once a year. The same habit that keeps you out of the credit card trap is the one that lifts your score.
New to borrowing? Start with good debt vs bad debt.
Questions people ask
What is a credit score?
A three digit number from 300 to 900 that lenders check before giving you a loan or card. Credit bureaus like CIBIL build it from your repayment record. A higher number signals that you repay on time.
What is a good CIBIL score?
There is no single official cutoff. Many lenders treat a score around 750 and above as strong, but it varies by lender and by the product you apply for. Aim as high as you can rather than at one magic number.
How can I check my credit score for free?
RBI has required each credit bureau to give one free full credit report a year, and many banks and apps show a score for free. Check the bureau's own site for the current process, and review the report for errors.
Does checking my own credit score lower it?
No. Checking your own score is a soft enquiry and does not affect it. Only a hard enquiry, when a lender checks because you applied for credit, can nudge your score.
What hurts my credit score the most?
Missing payments is the biggest factor. Heavy use of your card limit, many loan or card applications in a short time, and a very short history can also pull it down. CIBIL does not publish exact weights, so treat these as levers.
How long does it take to improve a credit score?
There is no fixed timeline. Paying on time and keeping your card usage low over several months usually helps, but it is gradual. There is no quick fix, and anyone promising an instant jump for a fee is best avoided.
Source: Credit bureaus (CIBIL, Experian, Equifax, CRIF High Mark) and RBI rules. CIBIL's exact formula is not public, so check cibil.com.
Flag a possible issue
Was this helpful?
Thanks for the signal.
Comments
Share your experience or a question. Be kind, stay on topic. This is reader discussion, not financial advice.
No comments yet. Be the first to share.