Sukanya Samriddhi Yojana: the girl-child savings scheme
A safe, tax-free, high-rate scheme to build a fund for a daughter
Saving for a child’s future feels daunting because the goal is far away and the amounts are large. Sukanya Samriddhi Yojana is a government scheme built for exactly one version of that goal: a long-term fund for a girl child. It pays one of the highest safe rates around, and the money grows tax-free.
How it works. A parent or guardian opens the account for a girl who is under 10 years old. You then put money in each year, and the balance compounds at a rate the government sets. Because it is a government small savings scheme, the money is safe, and the return is far higher than a regular savings account.
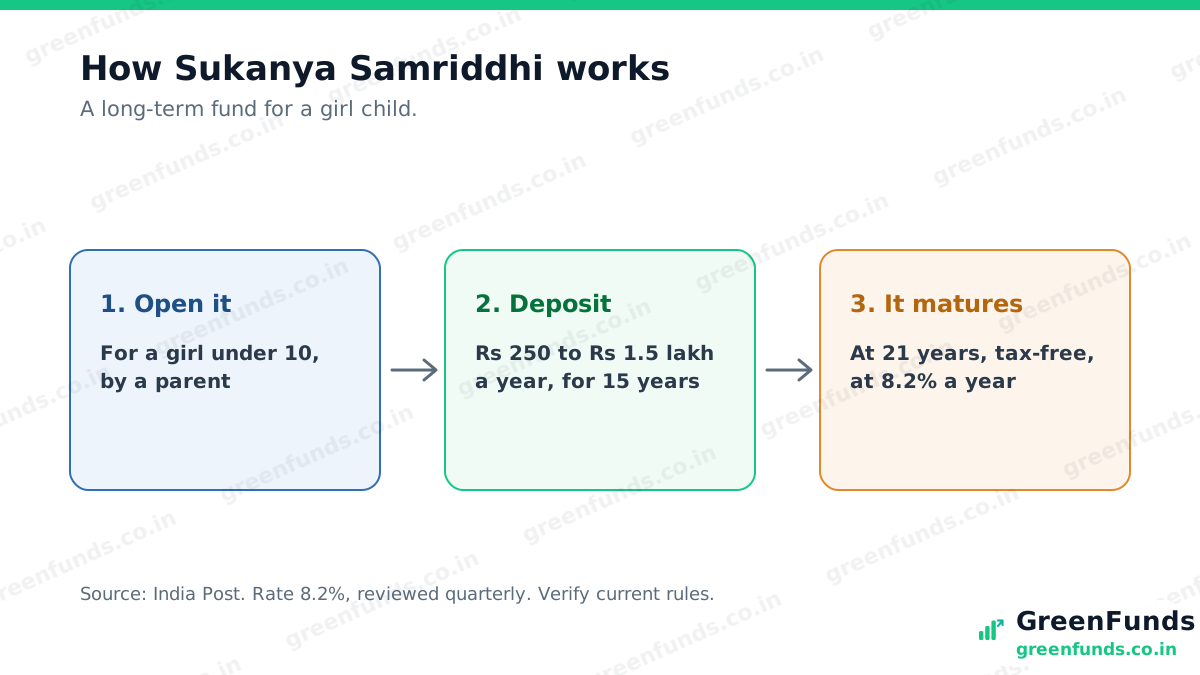
What it pays. The rate is 8.2% a year, compounded yearly, which is among the highest of all the government’s small savings schemes. That rate is reviewed every quarter, so over the account’s long life it can move up or down. Still, for a safe, long-horizon goal, it is hard to beat.
Did you know? Sukanya Samriddhi often carries the highest interest rate among the government’s small savings schemes, higher even than the public provident fund, and its interest and maturity are completely tax-free. For a long girl-child goal, that mix of a high safe rate and tax-free growth is unusually strong.
The rules to know. A few conditions shape how you use it.
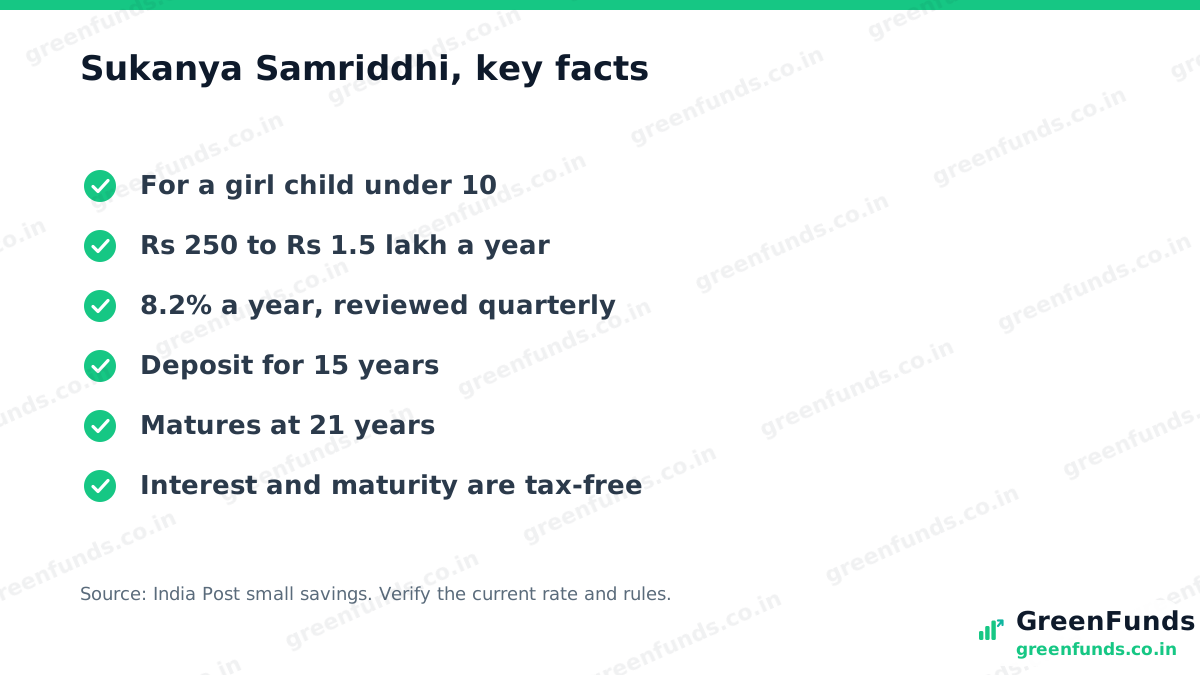
- You can deposit from 250 rupees up to 1.5 lakh rupees in a financial year.
- Deposits are required for 15 years; the account then earns interest until it matures at 21 years from opening.
- Part of the balance can be withdrawn for the girl’s higher education after she turns 18.
- The deposits, the interest and the maturity are all tax-friendly, with the interest and maturity tax-free.
The one trade-off. The money is locked for a long time, which is the point, but it means this is for a genuine long-term goal, not money you may need soon. Miss the yearly minimum and the account lapses until you revive it with a small penalty, so a standing instruction to deposit helps.
The takeaway. Sukanya Samriddhi Yojana is a safe, tax-free, high-rate way to build a long-term fund for a daughter. The price of that is a long lock-in, so use it for the far-off goal it is designed for, and confirm the current rate before you start.
More to read: the public provident fund, explained, PPF versus EPF, and the main tax-saving deductions.
Questions people ask
What is Sukanya Samriddhi Yojana?
It is a government savings scheme meant to build a long-term fund for a girl child. A parent or guardian opens the account for a girl under 10, deposits money each year, and the balance grows at a government-set rate. It is known for one of the highest safe rates among small savings, and for being tax-free.
What is the interest rate on Sukanya Samriddhi Yojana?
It is 8.2% a year, compounded yearly, which is among the highest of the government's small savings schemes. The government reviews the rate every quarter, so it can change over the long life of the account. Check the current rate on the India Post website before relying on it.
How much can I deposit and for how long?
You can deposit from 250 rupees up to 1.5 lakh rupees in a financial year. Deposits need to be made for 15 years from opening, and the account then continues to earn interest until it matures at 21 years from opening. If you miss the yearly minimum, the account can be revived by paying a small penalty plus the minimum.
Is Sukanya Samriddhi Yojana tax-free?
Yes. The deposits can qualify for a deduction on the old tax regime, and the interest and the final maturity amount are tax-free. That full tax-free treatment, combined with a high safe rate, is what makes it attractive for a long girl-child goal. Tax rules change, so confirm the current position before counting on it.
Source: India Post small savings scheme. Rate 8.2% a year (reviewed quarterly by the Ministry of Finance). Deposit limits, age and maturity per scheme rules; verify current figures on indiapost.gov.in.
Flag a possible issue
Was this helpful?
Thanks for the signal.
Comments
Share your experience or a question. Be kind, stay on topic. This is reader discussion, not financial advice.
No comments yet. Be the first to share.